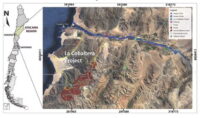
Chilean Cobalt Corp., through its subsidiary Baltum Minería SpA, will acquire mining concessions in the historic San Juan district of northern Chile for $28.3 million, payable in stages, along with royalty and other obligations. The transaction consolidates the past-producing La Cobaltera project area adjacent to the company’s existing properties, consisting predominantly of brownfield land with historical cobalt and copper production.
The acquired concessions include 1,381 hectares permitted for exploitation and 2,900 hectares for exploration. Combined with the company’s holdings at La Cobaltera and El Cofre, the owned and optioned position grows to 7,758 hectares for exploitation and 2,900 hectares for exploration.
The strategic logic rests on three verifiable factors. First, the company’s prior exploration demonstrated that modern methods can delineate mineralization around historical workings and support an independent resource estimate — while that work covered only a limited portion of the district’s mineralized trends. Second, historical tailings represent an additional development pathway alongside near-surface oxide mineralization and deeper sulphide targets. Third, metallurgical testing with prospective U.S. processing and offtake partners is underway to assess recovery options and commercial products, supporting the company’s stated objective of a Chile-USA supply chain for cobalt, copper, and other critical minerals.
Infrastructure de-risks the development case. La Cobaltera has road access, nearby power, proximity to the Port of Huasco, regional processing facilities, and an experienced mining workforce — conditions that support phased brownfield development beginning with near-surface oxide and transition mineralization while preserving deeper sulphide optionality.
The deal sits within an existing commercial framework: an executed cobalt-copper concentrate offtake agreement with Glencore, a processing letter of intent with U.S. Strategic Metals, and a $375 million project financing letter of interest from U.S. EXIM Bank for development at La Cobaltera and El Cofre.
Deal terms warrant scrutiny from a capital discipline standpoint. Upon exercise, sellers receive a 1.5% net smelter return royalty over the optioned concessions and certain existing Baltum La Cobaltera concessions for 99 years from commercial production. Baltum may repurchase half for $10 million within three years of commercial production, cutting the royalty to 0.75%, and holds rights of first refusal over initial royalty sales outside transfers to existing NSR beneficiaries or for estate purposes. Until acquisition or termination, Baltum pays $25,000 monthly rent, assumes concession patent fees and maintenance costs, and remits 20% of mineral sales after specified direct production and selling cost deductions.
The staged payment structure and royalty repurchase option reduce upfront capital at risk while preserving upside from resource expansion — a rational trade-off for a company still in the resource-definition phase. Key variables for investors to monitor: confirmation of resource growth across the consolidated district, metallurgical recovery outcomes, and conversion of the EXIM letter of interest into binding financing.
Source: https://www.e-mj.com/breaking-news/chilean-cobalt-consolidates-concessions/