Western tungsten prices have climbed to nearly four times those in China as export restrictions and US supply-chain policies fracture the market for the critical mineral, according to a new report by MetalMiner.
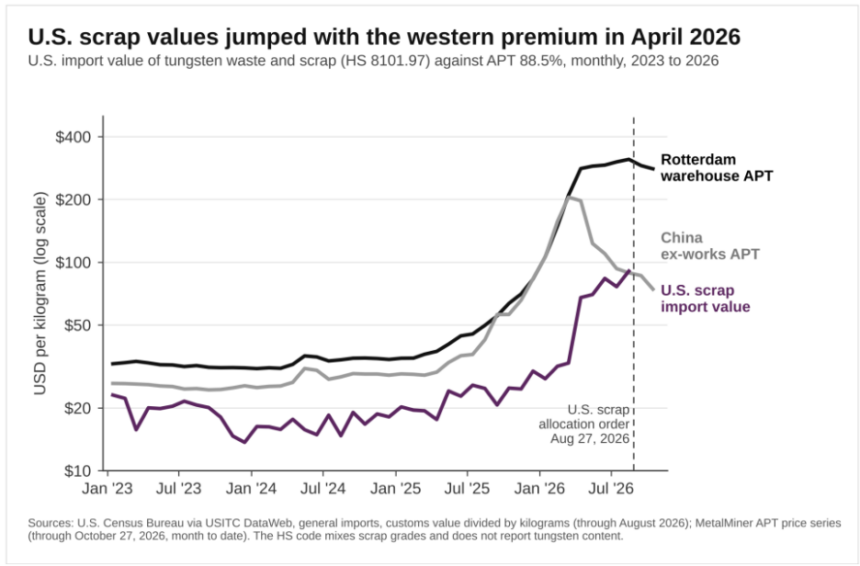
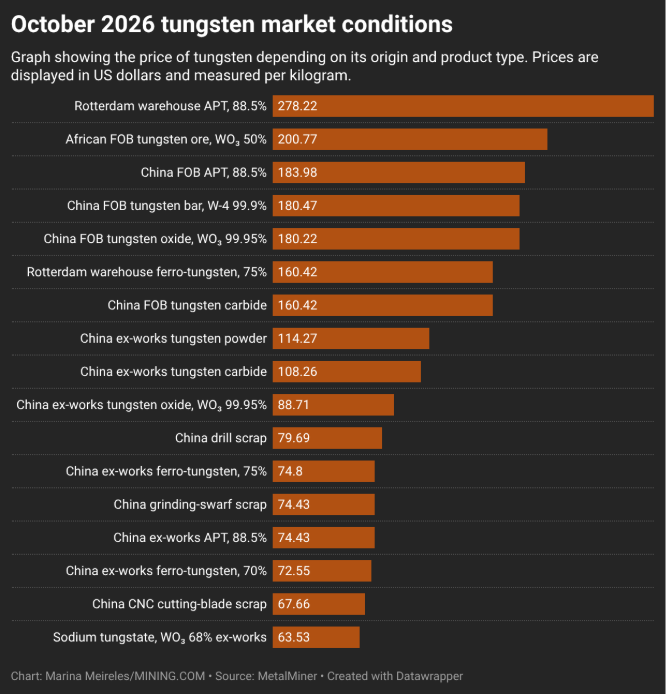
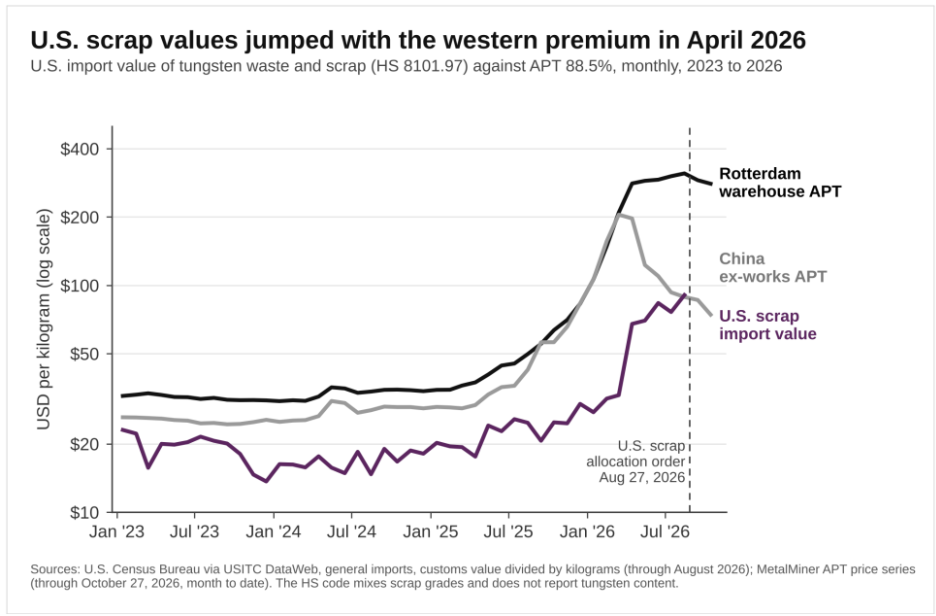
As a result of the rush to secure critical minerals and the restrictions and changes that came with it, Rotterdam ammonium paratungstate (APT) traded at $278.22 per kg in October, compared with $74.43 per kg for China ex-works APT, a 3.74-fold difference. The previous average between September 2021 and June 2025 was 1.24 times.
The widening gap reflects a market increasingly divided by regulatory compliance, geographic availability and processing capacity rather than a uniform global shortage, the report said.
Although US tariffs did have a certain impact on the western premium, it wasn’t anything too out of the ordinary, and after 14 tariff episodes, the premium widened about 11% over 12 months, against about 7% on regular days, the report said.
A disruption in tungsten availability can seem to be a regional premium, a widening product-form spread, or a tightening secondary-material market at first. Later on it becomes visible as delayed production, constrained tooling, or a reported defense supply-chain shortfall.
MetalMiner said it used structural insight to establish the risks, and market prices to monitor it in motion. The study used data through October 2026, with US data available through August.
Restrictions dictate
The report says that the question is no longer how much tungsten costs. It rather asks what the price and availability of traceable and qualified tungsten is in that form and geography, a result of the different restrictions imposed by China and the US on the product.
The China export licensing passed in February 2025 restricted tungsten exports from China and strengthened China’s pricing position.
What followed this move was a market split, with Rotterdam APT rising from a February 2025 average of $34.60/kg to a September 2026 average of $290.06/kg, while China ex-works APT rising from $28.92/kg to $86.02/kg on the same basis.
US tariffs on tungsten rose from about 4% (2015 to 2024) to 16.2% in December 2025, in an attempt to favour domestic supply. On top of tariffs, the US scrap allocation order effective in late August 2026 had the goal of keeping tungsten scrap covered by HTS in the country for domestic and defense use.
The next big move that will reshape the tungsten market again is set to happen on January 1, 2027, when the Defense Federal Acquisition Regulation Supplement (DFARS) procurement restriction is effective. The measure aims to restrict where tungsten used in the US is coming from, focusing on guaranteeing better traceability and domestic security for the US. The restrictions were set by the U.S. Department of Defense to limit how and from whom defense contractors can source materials, goods, and services to protect national security.
Diverging markets
APT pricing data collected by the report shows that market separation can be even more seen geographically.
In October 2026, Rotterdam warehouse APT at $278.22/kg was $203.79/kg above China ex-works APT at $74.43/kg, a 3.74x Rotterdam-to-China multiple. That multiple averaged 1.24 times from September 2021 to June 2025 and did not break out until April 2026.
The findings suggest that securing tungsten supplies will depend increasingly on access to qualified processing capacity and compliant material, rather than simply obtaining enough of the metal.
Between March and September 2026, using monthly averages, China ex-works APT fell 58% while Rotterdam APT rose 39%. The report asserts that this shows how China-origin and delivered-European APT markets are not behaving as one integrated market, a product of restrictions and competition for tungsten.
Future plans
The Western Tungsten market has an issue with conversion capacity rather than available scrap supply, sources told MetalMiner.
This means that scrap can accumulate unless conversion capacity grows in the US, which could then make western tungsten prices more similar to China’s. The report says that the US needs transparent and market based evidence to build its critical mineral supply chain, including tungsten.
MetalMiner’s report advises to keep track of important milestones for tungsten, such as the soon to be released US tungsten September 2026 data, the implementations of restrictions in 2027 and how the market sentiment changes through it all.
Source: https://www.mining.com/western-tungsten-prices-nearly-quadruple-chinas-report/