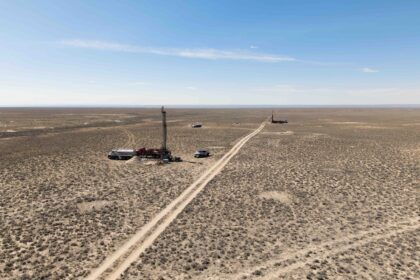
Zoomlion just delivered another 100+ wide-body mining trucks to CMOC’s Kisanfu copper-cobalt mine in the DRC, pushing the fleet past 200 units. All in full operation. Here’s what this really means — and it’s less about trucks than you’d think.
Let’s start with the ownership structure, because that’s where the real story lives. KFM Holding owns 95% of the mine (the DRC state takes 5%, standard extraction economics), and that holding is split 75% CMOC, 25% CATL via Ningbo Brunp. Read that again: CATL, the world’s largest battery maker, has a direct equity stake in the world’s largest cobalt mine. That’s vertical integration in its rawest form. When a battery manufacturer owns the mine that feeds its batteries, you’re not looking at a customer-supplier relationship — you’re looking at a company insulating itself from the commodity cycle. Smart, if cobalt prices hold. Painful if they don’t, and cobalt has been a miserable trade for years thanks to oversupply and, frankly, a glut of DRC output that nobody in the sector has the discipline to restrain.
The expansion itself is real. KFM Phase II is expected online in 2027, adding 7.26 Mt/y of ore processing and 100,000 t of annual copper capacity on top of the existing line’s 200,000 t of copper and 50,000 t of cobalt. This isn’t the first time we’ve seen this circus — Chinese-backed operators announcing aggressive African expansions — but CMOC has actually executed at Tenke Fungurume and KFM before, so the track record earns some benefit of the doubt. Still, 2027 timelines in the DRC carry infrastructure risk that a press release never mentions: power supply, logistics corridors, and political extraction all have a way of eating projected returns.
Now, the equipment angle. Zoomlion, a Chinese machinery conglomerate better known for cranes and concrete pumps, is now supplying heavy mining trucks at scale to one of the most demanding mining environments on the planet. The ZT115G series carries an 80-tonne payload and is built for continuous heavy loads, long hauls, steep ramps, and dust that destroys anything not engineered for it. The DRC copper belt is exactly where Western OEM names — Caterpillar, Komatsu, Hitachi — have historically owned the market.
That’s changing, and it’s changing fast. Zoomlion reports African dump truck sales doubled year-on-year through the first three quarters of 2026. Here’s what this really means: Chinese OEMs are running the classic playbook — undercut on price, deliver adequate equipment, and stack the deck on local service networks with on-site technical teams and spare parts inventories. In mining, uptime is the entire game. A truck that costs 20% less but sits broken for weeks is a bad deal; a truck that costs 20% less with a resident service crew is a great one. Zoomlion is betting on the latter, and CMOC’s repeat order — over 100 units already in the field, then 100+ more — suggests the bet is paying off operationally, not just on paper.
Take the vendor claims with a fistful of salt, though. Phrases like “benchmark status in mining equipment” and “vividly reflects deep cultivation of the African market” are marketing copy, nothing more. Two decades of watching equipment vendors will teach you that the first fleet’s performance and the second fleet’s durability are different questions. The real test comes at year four or five, when frames fatigue, transmissions start failing, and maintenance costs decide whether the total cost of ownership math actually worked. A repeat order after roughly a full operating cycle is a meaningful data point — but it’s one data point from one customer with a related-party flavor, given both parties are Chinese nationals with strategic alignment. CMOC buying Chinese trucks is partly procurement logic and partly geopolitics. Don’t confuse it with a clean market verdict.
The investment takeaways, plainly:
First, the copper thesis keeps getting structural support. Another 100,000 t of annual copper capacity coming online in 2027, on top of existing supply, from a low-cost jurisdiction — that matters for anyone tracking the medium-term copper balance. The supply response is real, and it’s coming from places the Western majors aren’t investing in.
Second, cobalt remains a supply story, not a scarcity story. The world’s largest cobalt mine is expanding while cobalt prices languish. If you’re long cobalt hoping for a squeeze, ask yourself who’s incentivized to hold back DRC tonnes. Nobody. CATL’s equity stake locks demand on one end but doesn’t fix the oversupply on the other.
Third, the OEM shift is an investable trend with a warning label. Chinese machinery names are taking share in emerging-market mining at a pace the legacy players dismiss at their peril. But this is a margin-compressing, service-heavy business, and share gains won’t mean much if warranty costs and field failures catch up. Watch backlog, service revenue, and any signs of fleet reliability issues before chasing the headline growth.
Fourth, jurisdiction risk is the perennial discount. Lualaba Province produces world-class copper, but it sits inside a country with a history of mining code rewrites, export bans on cobalt concentrates, and resource nationalism that resurfaces every cycle. The 5% state stake is the polite version of that reality. Anyone modeling these assets should carry a fat risk premium and assume the rules can change mid-expansion.
Bottom line: a solid operational story wrapped in promotional language. The fleet expansion is real, the copper is real, and the Chinese OEM encroachment on Africa’s mining equipment market is one of the quieter structural shifts of this decade. But none of it changes the oldest rule in the resource business — the commodity price decides everything, and the press release decides nothing.