




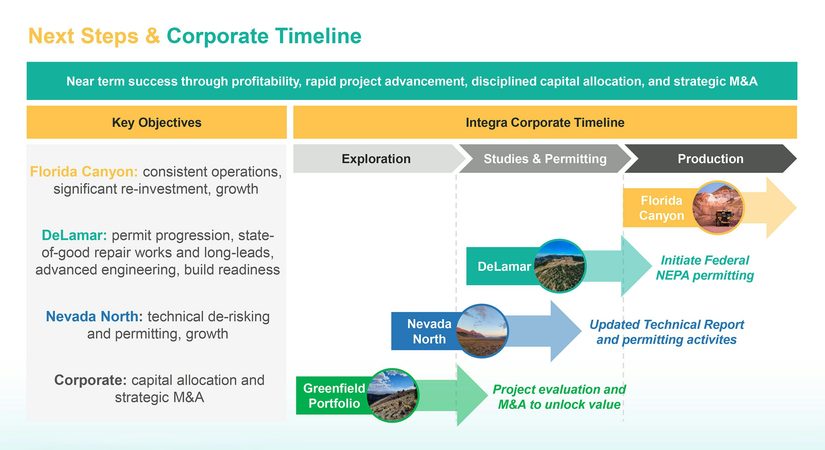
Integra Resources cut its 2026 production guidance from 70,000-75,000 ounces to 59,000-62,000 ounces. That’s an 11,000-13,000 ounce miss. The stock sold off, the headlines screamed, and half the retail crowd hit the eject button. Meanwhile, anyone who can read a cash flow statement shrugged. Let me explain why.
First, the actual problem. Q3 production was just over 17,600 ounces — solid — but the leach rate at Florida Canyon isn’t keeping pace with record mining rates. The company was mining lower-grade ore while running a deferred stripping campaign at the Central Pit, the location of the higher-grade material. Add fines in the ore and a blending strategy that needed refinement, and leach kinetics slowed down. The key detail everyone glossed over: the ounces are stacked on the pad. They’re not lost. They’re just arriving later than the guidance spreadsheet assumed. This is a timing problem, not a value-destruction problem — unless you’re the type who can’t tell the difference, in which case you probably shouldn’t own junior miners at all.
Lower-end guidance implies roughly 12,300 ounces in Q4; upper end, about 15,300. Down from what? Probably, yes. A catastrophe? Do the math before you panic-sell into someone else’s bidding opportunity.
Now the part that actually matters: the cash flows. Q3 revenue was $72.4M, mine operating earnings of $23.3M, operating income of $15.4M — and that includes $4.5M of expensed exploration, which is discretionary spending masquerading as a cost. Net income came in at $12.9M, or $0.064 per share (just under C$0.09 at 1.40 CAD/USD).
Operating cash flow was $21.8M, but strip out the flattering bits and the annoying bits: $1.8M went into working capital, only $575,000 of the $2.2M in accrued taxes was actually paid in cash, and there were $3.1M in lease payments against $0.8M of interest income. Adjusted operating cash flow: roughly $19.6M. The company invested $16.4M during the quarter — fully covered, no financing needed. Net cash position, finance expenses of a rounding-error $0.15M. While everyone was crying about guidance, the machine printed money and funded itself.
Yes, cash costs were $2,419/oz. Expensive, sure — against a realized gold price of $4,272/oz on 16,760 ounces sold. That’s a gross margin most S&P 500 companies would commit crimes for. Sustaining capex of $10.6M was actually down 30% year-over-year, which tells you the catch-up spending from the acquisition is winding down. People anchor on the cost number and forget the spread. That’s why they’re renting stocks and you should be owning businesses.
The strategic logic here is the only thing worth underwriting. Integra bought Florida Canyon specifically so it wouldn’t have to crawl back to capital markets every year with a dilution offering to fund DeLamar. Adjusted sustaining free cash flow in the first nine months of 2026 already exceeded $20M — meaning the acquisition has paid for itself in under a year. Compare that to the alternative: repeated equity raises at junior-miner discounts that permanently transfer 10-20% of your ownership to financiers each cycle. Dilution is the silent wealth-transfer mechanism of this sector, and Florida Canyon is the firewall.
DeLamar is the actual prize. The company spent $9.6M on it in Q3, including $4.2M on permitting and engineering and a $2M deposit on long-lead items. It’s in the FAST-41 permitting process, which gives roughly 15 months of timeline visibility — rare in this industry. At $3,000 gold and $35 silver, the after-tax NPV5% is $774M. At $4,500 gold and $65 silver, it’s $1.9B. Gold recently dipped below $4,000 and silver sits near $50, so the current-case NPV lands somewhere in that wide band. Notice I’m not pretending to know which. Anyone quoting you a precise NPV off a precise commodity price forecast is selling you certainty that doesn’t exist. What exists is torque, and DeLamar has plenty of it.
Nevada North gets an updated technical report in 2027, and the 2023 PEA used a laughably stale $1,700/oz gold base case. Recalculating at $3,000+ gold should mechanically inflate the NPV and


