The headlines are shouting about doubled profits. The charts have been signaling this for over a year. Price is the truth, and in China’s rare earth complex, price told anyone paying attention that the 2024 capitulation low was the trade of the cycle.
Two of China’s largest rare earth producers more than doubled net profits in the first nine months of 2026 versus the same period last year. China Northern Rare Earth (600111.SS) reported net earnings of 3.65 billion yuan (US$547 million), while China Rare Earth Resources and Technology (000831.SZ) posted 408 million yuan (US$61 million). The fundamentals are merely confirming what the tape already priced in — NdPr oxide has been in a stair-step uptrend since the April 2025 base, and the earnings simply caught up to it.
China Northern Rare Earth’s revenue rose 36.5% with net profit up 136.6%. China Rare Earth Resources and Technology delivered 6.5% revenue growth against 112.4% earnings growth. Read that asymmetry carefully: when profit growth massively outpaces revenue growth, you are looking at operating leverage against a rising price environment. That is margin expansion, not volume-driven growth. It is also exactly what you expect at this stage of a commodity upcycle — the same unit sales, repriced at 48–60% higher realizations, dropping straight to the bottom line.
Bayan Obo: Supply Expansion Is Not Price Expansion
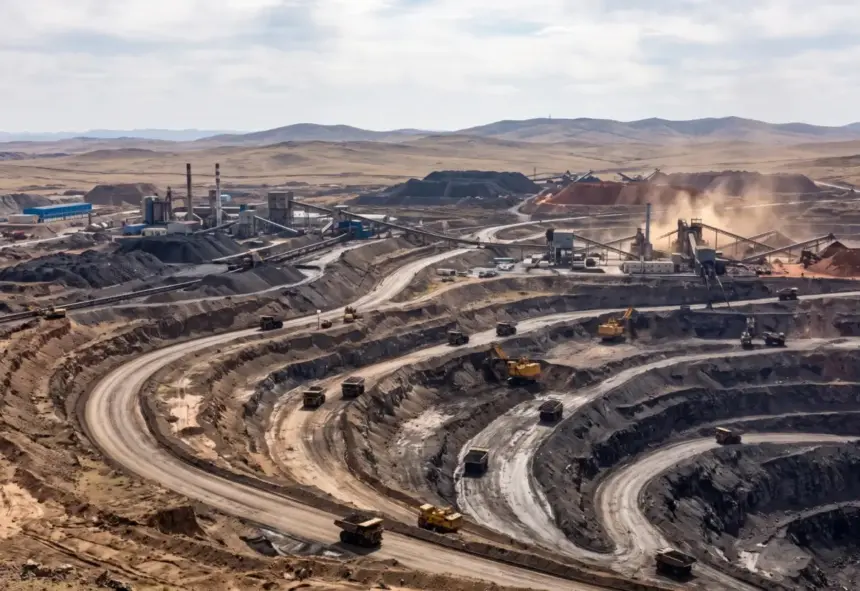
China Northern Rare Earth draws its feedstock from Bayan Obo in Inner Mongolia, the world’s largest rare earth deposit. The complex also carries substantial iron ore, niobium-bearing minerals, and fluorite, with rare earth concentrates recovered from iron ore processing streams and routed to downstream separation facilities.
In August, Baogang Group announced plans to lift annual mining capacity at Bayan Obo by 50%, driven primarily by iron ore economics. The headline sounds supply-bearish for rare earths. It is not — at least not directly. Commercial rare earth output remains chained to recovery rates and government processing allocations, and those allocations, not mining tonnage, are the binding constraint. More rock through the mill does not mean more oxide on the market when the quota system caps separation volume. Traders who sold the news on that August announcement learned the difference between raw extraction capacity and controlled end-product supply.
The Concentrate Price: A Quarterly Benchmark Worth Watching
In October, Baotou Steel and China Northern Rare Earth set a new concentrate transaction price of 38,769 yuan (US$5,793) per dry tonne for 50% REO material, excluding tax. That is approximately 48% above the corresponding period last year.
This is not a spot print — it is a quarterly benchmark under an established related-party pricing mechanism, adjusted against rare earth oxide market data. That makes it a clean proxy for the trend, free of the noise you get in thinner spot markets. When the benchmark ratchets higher quarter after quarter, the uptrend is confirmed on the fundamental ledger as well as the chart. Four consecutive higher quarterly prints would constitute the commodity equivalent of a confirmed trend structure: higher highs, higher lows, no distribution.
Watch the mechanics though. Higher concentrate prices are revenue upside for mineral suppliers and cost pressure for processors. The margin is migrating upstream. If you trade this sector, you need to know which side of that transfer any given name sits on.
Quotas: The Supply Curvature Nobody Else Has
China maintains strict production quotas across mining, smelting, and separation, and has consolidated them under China Northern Rare Earth and China Rare Earth Group — parent of China Rare Earth Resources and Technology. In August 2025, the framework expanded to cover domestic processing of imported rare earth raw materials, with strengthened reporting and tracking requirements.
From a charting standpoint, this matters enormously. Most commodities you trade have supply curves that respond to price. This one does not, at least not cleanly. With China controlling approximately 69% of global mine production in 2025 (per the USGS), and quotas concentrated in two state-directed groups, supply is a policy variable, not a market variable. That flattens the supply response and amplifies price moves when demand shifts. The 2024 downturn that crushed margins was the flip side — quotas were loose relative to demand, and prices bled out. The current quota discipline is the structural support underneath the rally.
Translation for traders: do not model this like iron ore or copper. The government’s quota decisions function like a central bank for oxide supply, and a change in quota policy is the single highest-impact event risk in this sector. There is no technical setup that protects you from a supply-side policy shift.
The NdPr Chart: Textbook Trend Resumption
Neodymium-praseodymium oxide has climbed roughly 62% since April 2025 per Shanghai Metals Market data. The recovery followed the 2024 downturn that stripped profitability from the entire Chinese rare earth industry.
Technically, this is one of the cleaner commodity reversals of the past two years. The 2024 selloff was a prolonged markdown with no signs of accumulation — declining volume on rallies, capitulation on the lows. The April 2025 base marked the transition, and the subsequent advance has shown the characteristics of a genuine trend: persistent higher highs and higher lows, strong volume on up-moves, corrective phases that hold above prior support without giving back trend gains. A 62% move without a single violation of structural support is not a squeeze — it is a re-rating.
Demand drivers are real and measurable: permanent magnet manufacturing for EVs, wind turbines, and industrial machinery. But the demand story is secondary. The chart led, the earnings followed, and the supply constraints are doing the heavy lifting on price.
What the Confirmations and Divergences Say Now
China Northern Rare Earth also reported record production of its main separated rare earth products, with higher sales of metals, magnetic materials, and polishing products. Volume growth layered on top of price growth — that is demand validation, not just repricing of existing inventory.
For China Rare Earth Resources and Technology, the 6.5% revenue figure against 112.4% profit growth deserves scrutiny. A pure price-taker with flat volumes has less earnings durability than a peer growing both. If NdPr consolidates or retraces, that name has less cushion. Momentum traders should note the distinction between the two — one is riding a trend with operating expansion, the other is a leveraged play on the price line alone.
Where are the risks? After a 62% advance and a doubling of producer profits, the easy money is made. Price is extended above its April 2025 launch zone, and the probability-weighted scenario from here is consolidation with a higher-low structure, not an immediate continuation leg. Pullbacks that hold above the quarterly concentrate benchmark’s implied cost support would be constructive. A break of the trend structure on rising volume would be the first objective signal of distribution — and given the state’s role in supply, it would likely precede any policy headline, not follow it.
The setup remains valid. The trend is intact, the benchmark is rising, and quota policy keeps the supply side compressed. But discipline over enthusiasm: buy structure, not headlines. The doubling of profits was confirmation of a move already 18 months in the making — the actionable question now is whether the next higher low forms cleanly, or whether this cycle tops while the news flow is still bullish. Watch the tape. It will tell you first.