




Generation Mining has started construction on its Marathon copper-palladium project, which is the only part of this story that matters. Everything else—soil sampling, “new geological frameworks,” prospects with charming names like Skipper and Boyer—is exploration theater, and you should price it accordingly.
Let’s deal with the facts. The company wrapped up its 2026 regional program: 1,786 soil sampling stations across 10 kilometers of strike length at Four Dams, Lacobeer, Skipper and Boyer, targeting hanging wall copper potential flagged back in 2024. About half the assays are in. The company says Lacobeer and Four Dams show the most “continuous coverage” of soil results. Translation: dirt anomalies. Soil samples are the cheapest, lowest-resolution data point in the entire exploration chain. You cannot underwrite a position on them. Anyone who does deserves the dilution they’ll receive.
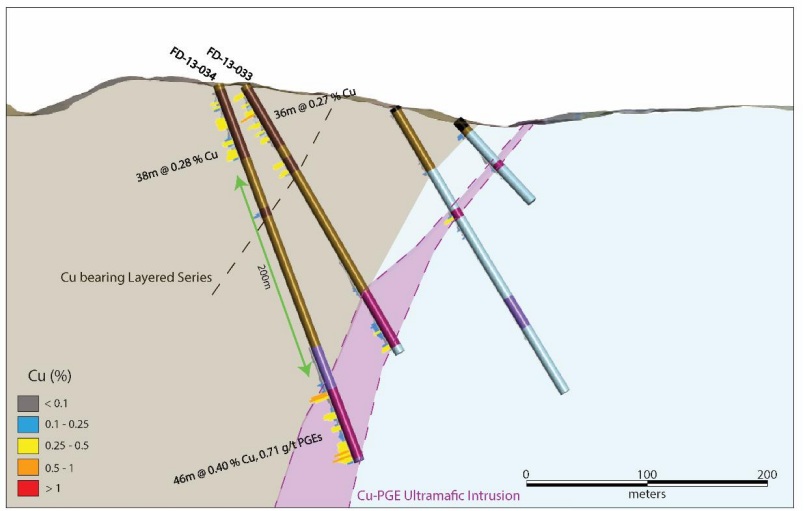
The only number worth circling comes from a drill program—thirteen years ago. At Four Dams in 2013, the drill bit hit 38 meters at 0.28% copper and 48 meters at 0.31% copper. Now, two things. First, those grades are modest—this is bulk-tonnage arithmetic, not a bonanza intercept, and the copper price and recovery assumptions determine whether it’s anything at all. Second, and more damning: nobody followed up on it. For over a decade. Either prior management was asleep, or someone ran the numbers and decided the targets weren’t worth a drill rig. Generation Mining will re-log and re-sample the core in Q1 2027, and I’d suggest you wait for that work before getting excited, because historical holes that sat ignored for 13 years are a hypothesis, not an asset.
The Big Rock Exploration “new framework” for copper in the Layered Series is exactly the kind of language juniors use to justify the next raise. Frameworks don’t produce cash flow. Mines do.
Here’s the actual investment case, and it’s binary: Marathon is a real, permitted, construction-stage copper-palladium project in Ontario. Its value will be set by capex discipline, financing terms, copper prices, and execution—full stop. The regional exploration is upside optionality bought with shareholder money, and dilution is the hidden expense ratio of every junior miner. It never shows up on a fee table, but it compounds against you relentlessly. If Marathon delivers, the exploration is a rounding error. If Marathon stumbles, no amount of soil geochem at Lacobeer saves you.
And yes, note the disclosure: the author owns shares and the company sponsors the website. That doesn’t make the facts wrong—the drill results are the drill results—but it does mean you’re reading marketing with footnotes. Adjust your confidence accordingly.
A soil sample tells you where to drill. A drill hole tells you where to mine. Only one of them has ever paid for anyone’s retirement.


