# Element 29 Is Lighting Money on Three Drill Rigs at Once — Here’s What You’re Actually Buying
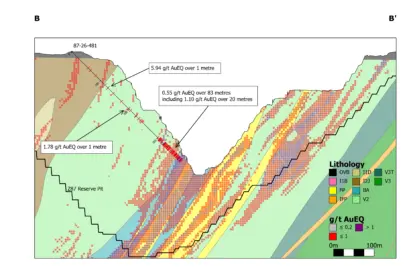
Element 29 Resources (ECU.V) is adding a third drill rig at its Elida copper-molybdenum-silver project in Peru, targeting Zone 4, a porphyry stock west of Zone 1 with visible copper-oxide staining and anomalous copper-moly geochem. The company will now likely blow past its planned 10,000 meters for 2026, and total drilling could exceed 30,000 meters with work extending into 2027 — possibly a fourth rig coming.
Let me translate the promotional spin into English: this is a junior miner burning cash faster to feed you more press releases. Every additional rig accelerates dilution, not value. The market cap of a junior explorer doesn’t grow because it drilled more meters; it grows because the numbers justify a mine, and almost none do. The odds that this ends in production rather than a shell are historically miserable, and you should price that in before you get romantic about “copper being the future.”
The existing resource, for what it’s worth: 322 million tonnes at 0.32% copper, 0.029% molybdenum, and 2.61 g/t silver. Run the math. The copper carries this — roughly 2.2 billion pounds of contained copper at an average grade that sits well below many producing operations. Grade is destiny in mining: lower grade means more tonnes moved per pound recovered, which means higher capex, higher opex, and thinner margins the moment copper prices sneeze. The moly and silver are rounding errors on a spreadsheet, not economics. If your thesis requires three metals to be simultaneously favorable, you don’t have a thesis, you have a hope.
Now the disclosure, which you should tattoo on your forearm before reading another word: the author holds a long position and Element 29 sponsors the website. That’s not a red flag; it’s a red banner. When the person telling you the story gets paid by the company and owns the stock, your skepticism should be operating at maximum. This is precisely why my core portfolio is boring, low-cost index funds where nobody sponsors the narrative. Every dollar sunk into a speculative explorer is a dollar not compounding at market returns. Put $10,000 into this and a broad market index, and over 20 years the gap isn’t thousands of dollars — it’s potentially a six-figure difference. Opportunity cost is the silent killer of retail portfolios, and juniors are its favorite hunting ground.
Yes, a discovery hole at Zone 4 could send shares up 50% in a week. It could also assay to nothing, and statistically, that’s the far more likely outcome. Step-out holes beyond the current resource are how you find out your deposit is smaller than hoped — that’s not upside, that’s a coin flip dressed in geological terminology.
The site itself admits you may lose your entire investment. Take that sentence seriously, because the promotional copy certainly hopes you won’t. Speculation money should be capped at what you can torch without flinching — and if you’re serious about financial independence, that number is probably smaller than your ego thinks.
Three drill rigs, 30,000 meters, endless assays: none of it changes the arithmetic. Drilling doesn’t create value. Economics do.
Source: https://www.caesarsreport.com/blog/element-29-resources-adds-third-drill-rig-to-elida-drill-program/