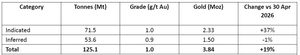
Aurum Resources just bumped its Boundiali resource to 125 million tonnes at 1 g/t for 3.84 million ounces, with roughly two-thirds now sitting in the indicated category. The reserves currently stand at 1.21 million ounces, and an updated reserve will come with the definitive feasibility study expected by the end of this year. If that lands on schedule, first gold is targeted for the first half of 2028.
Now, let’s talk about the number everyone in junior mining conveniently ignores: grade. 1 g/t is not a grade, it’s an apology. Yes, open-pit operations can chew through it in Côte d’Ivoire with reasonable stripping, but every dollar of all-in sustaining cost is hanging on assumptions—mill throughput, strip ratio, recovery, and gold not deciding to revisit $1,600. “4 million ounces in the ground” is not 4 million ounces of profit. The ground doesn’t care about your spreadsheet.
The bull case here is actually arithmetic, which is refreshing in a sector allergic to it. Market cap is A$260M, with almost A$100M in cash, so enterprise value is roughly A$160M against 5 million ounces across Boundiali plus the 1.16-million-ounce Napié project. That’s about A$33 per ounce in the ground—under US$25. Compare that to takeout prices for producing West African assets, and the math isn’t stupid. Yet.
The caveats are where amateurs get slaughtered. A resource conversion bump from inferred to indicated means nothing until a reserve statement confirms economics. A$100M in cash funds the 150,000-meter drill program, sure—but feasibility studies have a nasty habit of requiring follow-on capital, and every equity raise in a A$260M company dilutes your per-ounce exposure while management’s percentage stays suspiciously intact. And Côte d’Ivoire is comparatively well-run by West African standards, which is like saying a boat is comparatively dry. Jurisdiction risk is real, it’s unhedgeable for retail, and it’s why the per-ounce discount exists in the first place.
And can we retire “in the ground” valuations as a standalone metric? Two projects can both trade at A$33 per ounce while one prints cash and the other consumes it until the heat death of the universe. Grade, metallurgy, infrastructure, and permitting separate the two. The market cap-to-ounce ratio tells you what you’re paying for a lottery ticket, not what you’ll receive.
If you own this, fine—I hold speculative positions too, sized appropriately. But if your portfolio’s FIRE timeline depends on a pre-production, single-asset, sub-1-gram junior hitting feasibility, first gold, and first cash flow in sequence without a stumble, your problem isn’t stock selection. It’s savings rate. No per-ounce discount fixes a plan that requires everything to go right.
The feasibility study lands by year-end or it doesn’t. Everything else is noise until then—and the market will still be pricing lottery tickets in the ground long after you’ve learned what this one was worth.