
Strip the headlines away and this is a supply-chain restructuring story, and supply-side changes are where margin expansion or compression gets priced in long before the narrative catches up. Guinea has opened its first industrial gold refinery in Conakry — the Nimba Gold Refinery — with initial processing capacity of 530 tonnes per year, scaling to 733 tonnes at full build-out. That figure matters less for what it is and more for what it implies: capacity roughly ten times the country’s recorded 2025 gold exports of 72.12 tonnes. When capacity outruns supply by an order of magnitude, throughput assumptions are fiction until volumes confirm them. Price is the truth, and volume is the proof.
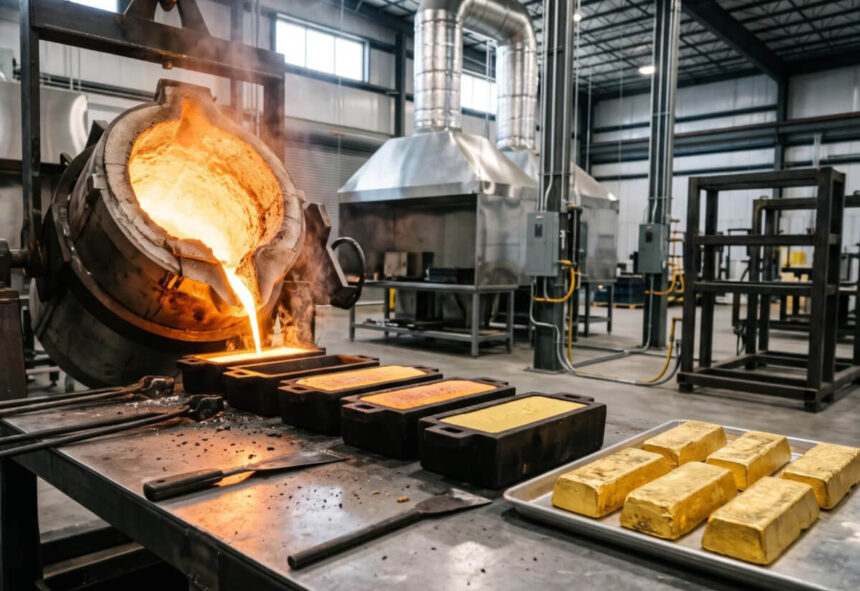
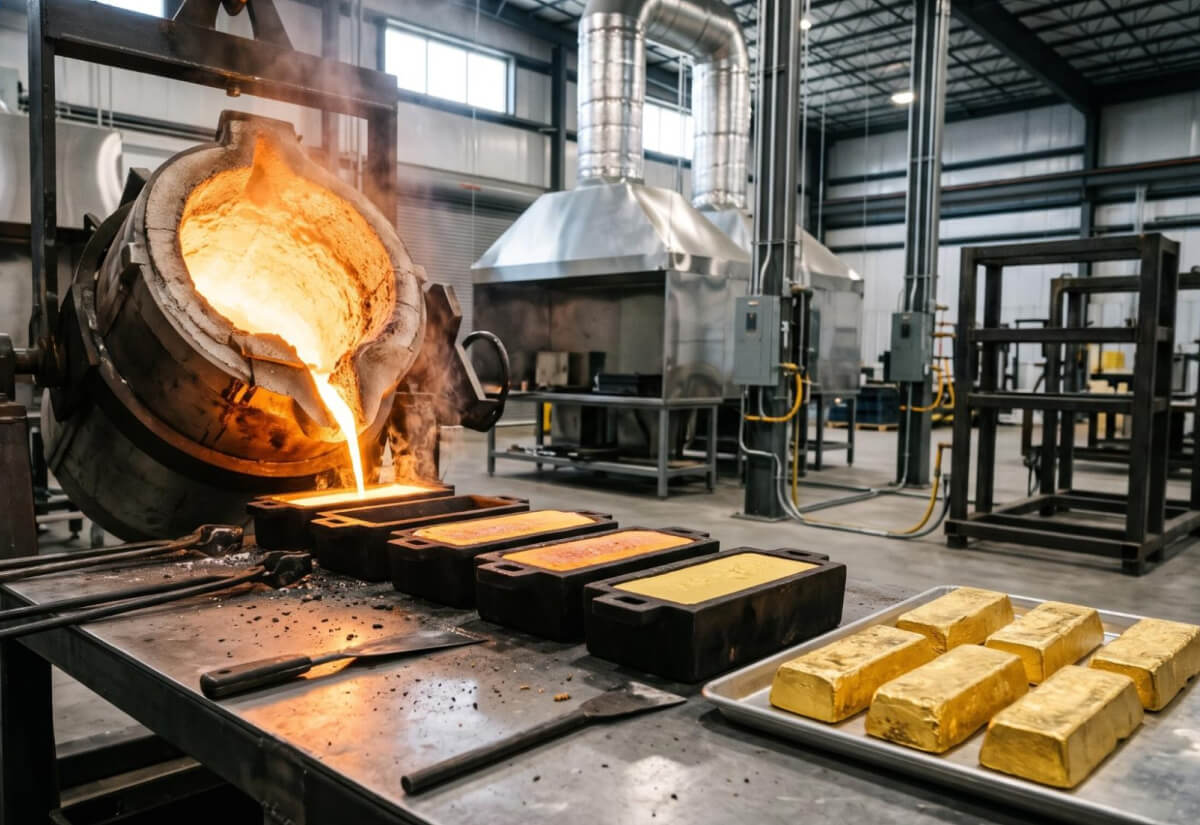
President Mamadi Doumbouya inaugurated the facility on November 1, 2026, at Cité de l’Air in the Gbessia district, with Prime Minister Amadou Oury Bah and Mines and Geology Minister Bouna Sylla present. The refinery is designed to produce bullion at up to 99.99% purity and exported its first batch of locally refined bars on October 9 — three days after the compliance deadline for the export ban expired. That sequencing is worth noting. The mandate went live before the infrastructure had proven it could run. First shipments within days of the deadline suggest the logistics were staged, not improvised, which reduces execution risk for producers operating in-country.
The Export Restriction: A Hard Level, Not a Suggestion
The domestic refining policy was announced June 19 following negotiations between Doumbouya and representatives across the mining spectrum — industrial, semi-industrial, artisanal, and trading houses. A presidential decree signed July 8 made local refining compulsory and gave exporters 90 days to comply. That window closed October 6.
The decree draws a clean line: raw gold is defined as any material below 99.5% purity, including doré, concentrates, ore, and alloys. Guinea-produced gold must now clear a government-licensed refinery before export. Think of this as a structural resistance level on the export pathway — no material passes below that purity threshold without being processed through the new channel. Levels like this don’t get negotiated at the margin; they either hold or they don’t.
Compliance friction is non-trivial. Exporters must file nine documents: certificates of origin and analysis, commercial invoice, customs declaration, proof of bank registration, an export permit from the Minister of Mines and Geology, and a compliance certificate from the Office Guinéen d’Expertise de l’Or, du Diamant et autres Matières Précies. Nine administrative checkpoints is a bottleneck by design. Every added step in the export chain increases the probability of delayed shipments and raises working-capital requirements for smaller operators. Watch the semi-industrial and artisanal cohorts — they have the thinnest balance sheets and the least capacity to absorb regulatory drag.
Enforcement carries teeth. Violations risk gold seizure or suspension of export authorizations, and the decree permits suspension or withdrawal of special authorizations under the Mining Code. Producers retain ownership of their refined gold absent a separate written agreement, with refiners charging processing fees negotiated with clients. That fee structure is the new cost basis on every ounce leaving the country — a direct spread compression on margins unless bullion pricing and capture rates offset it.
Capacity Versus Actual Supply: The Divergence That Matters
Here’s the number that should anchor any analysis. The Ministry of Mines and Geology reports 72.12 tonnes of gold exported in 2025, down roughly 2% from 2024. Industrial operators shipped 19.946 tonnes; semi-industrial companies, 2.565 tonnes. The remaining 49.609 tonnes — nearly 69% of recorded exports — came from artisanal mining.
Set the refinery’s 530-tonne initial capacity against that 72-tonne flow and you have a massive divergence between installed throughput and available feedstock. This setup lacks confirmation. A refinery running at 14% utilization doesn’t generate processing-fee revenue; it generates fixed-cost drag unless it sources cross-border material. The government has signaled exactly that intent — the facility could accept gold from neighboring West African producers, and actual volumes will depend on supply agreements with producers and traders. Whether regional doré migrates to Conakry is the variable that determines whether this capacity number is meaningful or decorative. Watch processing volume disclosures over the next two quarters. That’s the volume confirmation for this entire policy.
The 2% year-over-year decline in recorded exports is also worth flagging. Declining recorded output alongside a formalization push typically means a portion of production is moving through untracked channels. Artisanal gold, which dominates the export mix at 69%, is the leakiest segment to regulate. If the tracking systems (more on those below) don’t capture that flow, the refinery’s feedstock problem compounds.
The Central Bank Bid: A Potential Structural Floor
The more consequential development sits in the October 1 meeting between Minister Sylla, industrial and semi-industrial producers, and central bank vice-governor Mamadou Sylla. The proposal under discussion: the Central Bank of the Republic of Guinea would purchase up to 30% of participating companies’ gold production on behalf of the state, pay in Guinean francs, and record the metal in its gold account.
A committed state buyer taking 30% of national output is, in effect, a price floor mechanism on the domestic market. If implemented, producers gain a guaranteed offtake channel; the trade-off is payment in local currency, which introduces FX exposure for companies that denominate costs in dollars. Whether that’s net positive depends entirely on the commercial terms — which is why the agreed technical committee, tasked with hammering out pricing, payment conditions, technical requirements, and delivery schedules, is the critical next step. A preliminary agreement followed by individual contracts is the roadmap. Until terms are signed, this is a headline without a chart. No position should be sized on it.
The July decree also mandates a national tracking system administered by the Ministry of Mines and Geology covering producer registration, reported output, movement of unrefined gold, and origin certificate issuance. Formalization pushes like this historically shift a percentage of artisanal production into the recorded economy — which would raise official export figures without any change in actual mine output. Anyone modeling Guinean supply should treat the 2025 baseline of 72.12 tonnes as understated and expect recorded volumes to rise mechanically as tracking tightens, independent of production growth.
What to Watch
Three data points will tell you whether this restructuring works. First, refinery utilization — if quarterly processing volumes climb toward even 100 tonnes, the capacity narrative has volume confirmation behind it. Second, recorded export totals in 2026 versus the 72.12-tonne 2025 base; a sharp jump signals formalization capture rather than organic growth. Third, the central bank purchase agreement — if it signs with favorable commercial terms, Guinea-listed and West African-focused producers gain a structural bid under domestic gold pricing, and that’s the kind of margin improvement markets re-rate.
Until then, treat the 733-tonne capacity figure as aspirational overhead resistance. The policy infrastructure is in place; the volumes haven’t validated it yet.
Source: https://www.miningfeeds.com/guinea-opens-first-gold-refinery-as-raw-gold-export-ban-takes-effect/