




So Aztec Minerals drilled nine more holes at Tombstone in southeastern Arizona, and all nine hit gold and silver in oxide rock. Fine. That’s a fact. Everything else in the average junior miner press release is narrative decoration, and decoration is where your money goes to die.
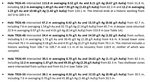
Here’s what the drills actually found: step-outs 90 to 190 meters west of the North Extension area, all mineralized. Hole TR26-45 returned nearly 116 meters at 0.67 g/t gold-equivalent. Hole TR26-48 cut 24.4 meters at 1.02 g/t gold-equivalent, roughly 75% of that being actual gold, the rest silver. The company thinks the oxide zone extends about 190 meters further west than previously known, and — this is the part they always say — mineralization remains “open” to the west, north, and at depth.
“Open in every direction” is the geology equivalent of a startup claiming unlimited TAM. It’s literally unfalsifiable until someone drills the boundary, and drilling costs money. Your money, incidentally, if you fund it through dilution, which is how junior miners routinely fund everything.
Let’s do the math the hype merchants won’t do for you. A bulk-mineable open-pit operation typically needs sustained grades well above 0.5 g/t gold-equivalent to clear its cost of capital, and a 116-meter intercept at 0.67 g/t AuEq is not a deposit — it’s a data point. Intercepts become deposits through spacing, consistency, and metallurgy, and none of that exists yet. What exists is a drill program that ran into old underground workings and had to skip unsampled intervals, which complicates continuity analysis whether or not it makes a good headline.
The genuinely important number arrives later this month: the maiden resource estimate. And note the fine print — it will NOT include these newest results, because they came in after the resource cut-off date. So the number you’ll see is, by construction, stale on arrival. It’s a floor, not a ceiling. Anyone trading the resource announcement as if it’s final information doesn’t understand how cut-off dates work, and there’s no reason to be that person.
Also worth stating plainly: this is a pre-resource exploration-stage company with no revenue, no PEA, no NPV, and a valuation that currently rests entirely on geological optimism. Position sizing here isn’t a portfolio allocation — it’s a lottery ticket with better odds and a longer wait. This is spec capital, money you can lose entirely without flinching, and anyone telling you otherwise is usually holding shares or a sponsorship invoice. Speaking of which: the author of the original piece holds a long position and Aztec sponsors the website. That doesn’t make the drill results fake, but it does mean every adjective in the write-up deserves a discount.
One more thing about the 2027 drill programs implied for this western area: every additional dollar of exploration is either discovering value or destroying it, and you won’t know which until the assays come back. Junior mining isn’t investing; it’s venture capital with core samples.
The resource number drops this month. If it can’t support the market cap, no amount of “open to the west” will save you — a hole in the ground doesn’t care about your thesis.
Source: https://www.caesarsreport.com/blog/aztec-minerals-expands-tombstone-mineralized-area-to-the-west/


