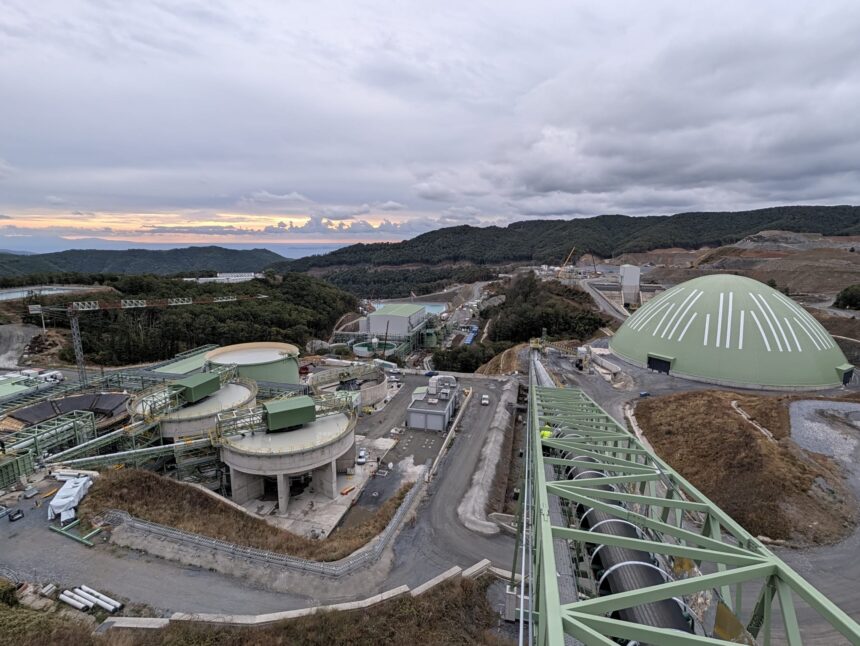
Eldorado Gold (TSX: ELD; NYSE: EGO) shares sank after the company slashed its annual production outlook and raised spending estimates as the Skouries copper-gold operation in Greece takes longer than expected to ramp up.
Vancouver-based Eldorado cut its 2026 gold forecast by 18% at the midpoint, to 425,000-475,000 oz. from 495,000-600,000 oz. previously. The miner also disclosed $160 million (C$224.6 million) in additional Skouries costs, plus $80 million of previously planned spending now expected before commercial production, according to quarterly results issued late on Wednesday.
While Skouries remains on track for commercial production by Dec. 31, “another capital increase and materially lower 2026 production reinforce execution concerns heading into 2027,” Jefferies mining analyst Fahad Tariq wrote Wednesday.
Eldorado dropped 6.1% to C$45.29 Thursday morning in Toronto, valuing the company at about C$11.9 billion ($8.5 billion). The stock has traded between C$34.25 and C$69.46 in the past year.
Execution concerns
The setbacks delay Eldorado’s transition from heavy construction spending to stronger cash generation from Skouries and Saskatchewan’s McIlvenna Bay.
As 2026 marks its fourth year of negative guidance revisions in the past five, “investors will question the company’s execution record,” Tariq said. He nevertheless maintained his buy rating on the stock.
Skouries’ expected gold output this year shrank to 10,000-35,000 oz. from 60,000-100,000 oz., a 72% reduction at the midpoint. Eldorado still expects commercial production late in the fourth quarter and says the slower start doesn’t change its expectations for the operation’s longer-term capacity.
Longer commissioning
Total project capital is now estimated at $1.43 billion, up $110 million, while accelerated operational capital rises $130 million to $390 million. Longer commissioning, additional contractor and owner costs and extended use of temporary generators contributed to the increase. Another $30 million could be incurred, depending on when commercial production begins.
National Bank Financial analyst Don DeMarco distinguished the additional costs from the reclassification of spending previously expected after commercial production. His calculation puts the underlying Skouries increase at $160 million, or 10%.
At Skouries, two of six tailings filter presses are operating; the other four are expected online in November. Temporary generators contributed to costs but have since been removed following the grid connection, the company said.
Existing mines
Weakness also extends to existing operations. Eldorado cut their gold forecast to 410,000-430,000 oz. from 430,000-490,000 oz., reflecting shortfalls at Kisladag in Turkey and Olympias in Greece. Stronger performance at Quebec’s Lamaque complex provided a partial offset.
At Kisladag, slower mining delayed access to higher-grade ore. The mine’s roughly 300-day leaching cycle means improved grades being stacked now won’t fully translate into production until late this year and into 2027. Olympias’ expansion schedule is reducing expected fourth-quarter throughput.
All-in sustaining cost guidance for existing operations climbed 16% at the midpoint to $1,975–$2,125 per oz., reflecting lower output, higher sustaining spending and price-linked royalties.
Cash burn
“Higher cost guidance largely reflects lower expected production, higher sustaining capex and increased price-linked royalties, rather than a deterioration in the underlying cost structure,” DeMarco wrote Thursday.
McIlvenna Bay, in Saskatchewan, is also expected to cost more. Capital expenditures are now estimated at $975 million, a 2.4% increase. It excludes earlier spending before June 2024. Commercial production is expected late in the fourth quarter.
Adjusted net earnings of 49¢ a share missed the 54¢ consensus estimate in the third quarter. The free cash flow deficit widened to $191.1 million from $87.4 million a year earlier as spending continued at Skouries and McIlvenna Bay. Excluding those two operations, free cash flow was positive at $98.3 million, the company said.
“Overall, despite an operationally weaker quarter, we believe that the guidance revision is necessary, as it provides Eldorado with a much more achievable target as it approaches the inflection point for a significant step-up in production in the near future,” CIBC mining analyst Cosmos Chiu wrote in a note.
Source: www.northernminer.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.