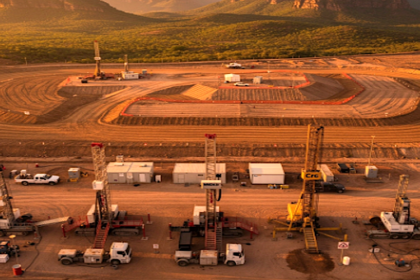

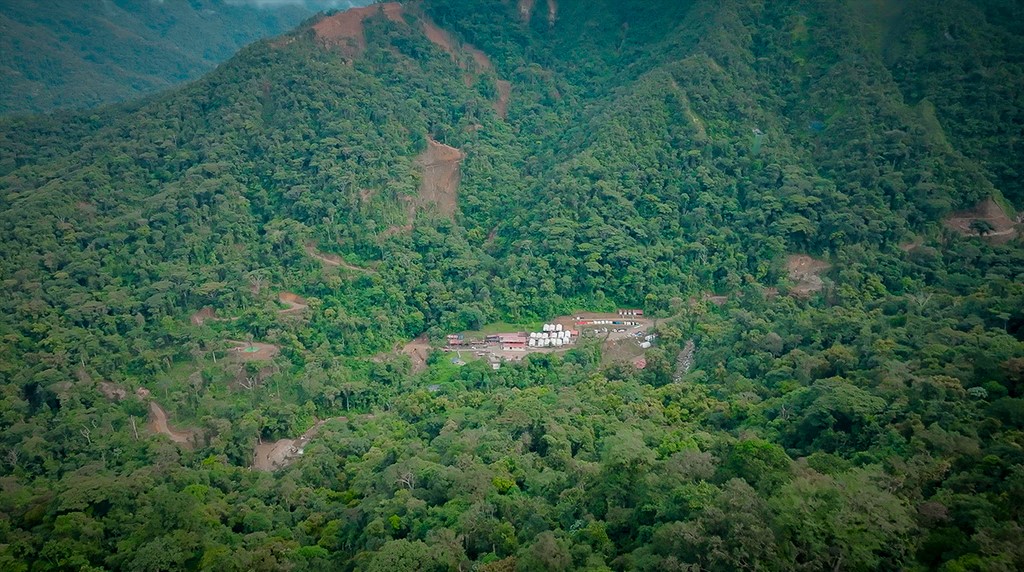
Image source: https://www.solarisresources.com/warintza
Price is the truth. Everything else — press releases, resource statements, permitting updates — is context that either gets validated by the tape or it doesn’t. Solaris Resources (TSX:SLS) is one of the few juniors where the catalyst stream has been dense enough to actually test that proposition. The Warintza Project in southeastern Ecuador is the asset behind the ticker, and the question a technician should ask is simple: has the price structure confirmed the de-risking story the company keeps printing? Let’s work through it.
Start with what Warintza actually is, because the technicals of a junior cannot be divorced from the milestone calendar that drives its re-rating cycles. The deposit was identified in 2000 by David Lowell and has since been delineated into a 5.8 billion tonne resource — one of the largest undeveloped copper inventories on the board. The Pre-Feasibility Study, released in late 2025, established a maiden reserve of 1.3 billion tonnes and a mine plan exceeding two decades, with first-five-year production modeled above 300,000 tonnes of copper equivalent annually. Strip ratio is low, early-year grades are front-loaded, and modeled operating costs sit in the industry’s lowest-cost quartile.
That’s the fundamental architecture. Now the tape.
Milestone Structure and How Price Responded
Development-stage juniors trade in a predictable pattern: accumulation during quiet drilling phases, markup into major catalysts, distribution or consolidation after the news hits. Solaris has followed that script closely. The PFS release functioned as a textbook sell-the-news event in the immediate aftermath — a common structure when expectations are priced in ahead of a binary milestone — but the subsequent price behavior is what separates a genuine re-rating from a one-off spike.
The key test came in April, when the company received technical approval of its Environmental Impact Assessment following a multi-year review. This was the single largest de-risking event in the project’s history. The critical observation is what happened after: price held its gains rather than fading them. When a junior absorbs a major positive catalyst and consolidates instead of bleeding back into the pre-news base, that’s structural confirmation. It tells you real money took the paper off weak hands and isn’t in a hurry to give it back.
Volume tells the same story. The EIA approval window printed some of the heaviest turnover in the stock’s recent history, and — this is the part most retail misses — the follow-through sessions did not show distribution characteristics. No long upper wicks on declining volume, no gap-fill behavior back toward the prior range. That’s orderly accumulation, not a blow-off.
Levels That Matter
Without cluttering this with extraneous lines, the framework is straightforward. The PFS-era trading range established the primary support zone. That zone was tested repeatedly through the winter and held on every approach — each retest on contracting volume, which is the classic signature of supply absorption. The EIA approval broke the stock out of that range, and the breakout was validated by expansion in participation. Price is now trading above the prior consolidation ceiling, which has flipped from resistance to support. That level is your risk reference. Below it, the breakout thesis is dead and the stock reverts to range-bound treatment. Above it, the path of least resistance remains higher into the next milestone window.
Watch the remaining permitting stages as the next re-rating catalysts. The company is progressing through Ecuador’s Free, Prior, and Informed Consultation process, targeting full approvals by end of 2026. These events create identifiable trade windows. The pattern to trade is the pre-announcement drift higher on building volume, followed by discipline around the event itself. If a milestone lands and price gaps up on volume that immediately contracts while price stalls, that’s exhaustion — take the trade off. If the gap holds and consolidates sideways on light volume, the trend is intact and the next leg usually follows within weeks.
What the Chart Still Needs to Prove
This setup is constructive but not flawless, and pretending otherwise is how accounts get run over. The stock has not yet printed a sustained breakout to new all-time highs on the kind of volume expansion that would signal institutional rotation into the name at scale. The moves off each catalyst have been real, but retrace analysis shows the advances have given back meaningful portions before basing. That’s characteristic of a junior still trading on event-driven flows rather than a committed institutional register — normal for the development stage, but it means position sizing should reflect wider expected drawdowns.
RSI behavior through the recent advance has been clean: momentum peaks with price peaks, no bearish divergence printed on the EIA run. If a divergence forms into the next catalyst window — price making marginal new highs while RSI rolls over — treat it as a distribution warning, not noise. MACD remains in bullish territory above the signal line on the daily, but the histogram is flattening, which is consistent with consolidation rather than fresh momentum. Wait for the crossover or the volume to decide the next directional leg. Guessing here is a coin flip dressed up as analysis.
The Workstreams That Drive the Next Legs
Two concurrent programs determine the milestone calendar, and each has tradeable implications. First, feasibility-stage drilling restarted last month at Warintza, targeting geotechnical and hydrogeological data for mine planning, infrastructure design, and tailings engineering. Drilling programs rarely move the needle directly at this stage — the resource is defined — but they sustain a cadence of newsflow that keeps the stock on screens. Steady drilling means steady volume baselines, which is exactly the environment where ranges compress before expanding. Compression after a validated breakout is accumulation, and the measured move from that base is typically substantial.
Second, financing is in place. Following key development milestones, Solaris unlocked an additional US$50 million under its Royal Gold streaming agreement, funding engineering, permitting, and exploration through the feasibility phase. From a technical standpoint, this matters because it removes the dilution overhang that haunts most juniors at this stage. A company that isn’t hitting the market for cash doesn’t produce the supply-driven chart deterioration — the relentless lower highs from placements — that keeps development-stage tickers in multi-year downtrends. Capitalized through feasibility is a structural tailwind for the chart, full stop.
Community alignment is the third variable, and while it doesn’t show up on a chart, it shows up in volatility. Warintza operates under an Impact and Benefits Agreement with local Shuar communities, supported by long-running engagement and education programs. Jurisdiction risk is the binary that technicals cannot price in advance. A formalized social license reduces the probability of gap risk from social conflict headlines. Lower tail risk means tighter stops are survivable, which directly improves the risk-reward math on every trade in the name.
Positioning Framework
The setup as it stands: trend is up on the higher timeframe, price holds above the flipped prior resistance, volume confirms the breakout rather than contradicting it, and momentum indicators show consolidation rather than deterioration. That’s a hold-and-add structure, not a chase structure. The add zones are the retests — the flipped support level, and deeper, the mid-range shelf from the pre-EIA consolidation where buyers demonstrated they would defend the stock on volume.
The invalidation is
Source: https://www.miningfeeds.com/building-the-future-of-copper-inside-solaris-resources-warintza-project/