

Rhodium prices are poised to fall as weakening autocatalyst demand pushes the market into surplus next year, though exceptionally thin inventories leave the rare metal vulnerable to sharp supply-driven rallies, according to TD Commodity Strategy.
TD projects rhodium will fall from about $9,000 an ounce to $7,600 in 2027 and $6,500 in 2028. After four consecutive years of deficits, the bank expects a 20,000-oz. surplus next year as rising mine and recycled supply combines with flat-to-declining consumption.
The shift would mark the market’s first surplus since 2022 and follow a projected deficit of about 50,000 oz. this year. TD said the balance could have turned earlier had production at South Africa’s Amandelbult platinum-group metals mine not been delayed by shaft collapses in 2025.
The bearish longer-term outlook comes with a significant caveat. Above-ground inventories are expected to fall to little more than three months of demand, leaving little room to absorb an unexpected disruption at a major mine or refinery.
Supply squeeze
Rhodium’s unusually long processing cycle compounds the risk. Moving material from mine production to refined metal takes more than three months, compared with just over a month for platinum and palladium, according to TD.
That constraint could produce sudden price spikes even as the broader market moves towards surplus because the industry is already operating near full capacity. A disruption could leave producers unable to quickly replace lost supply.
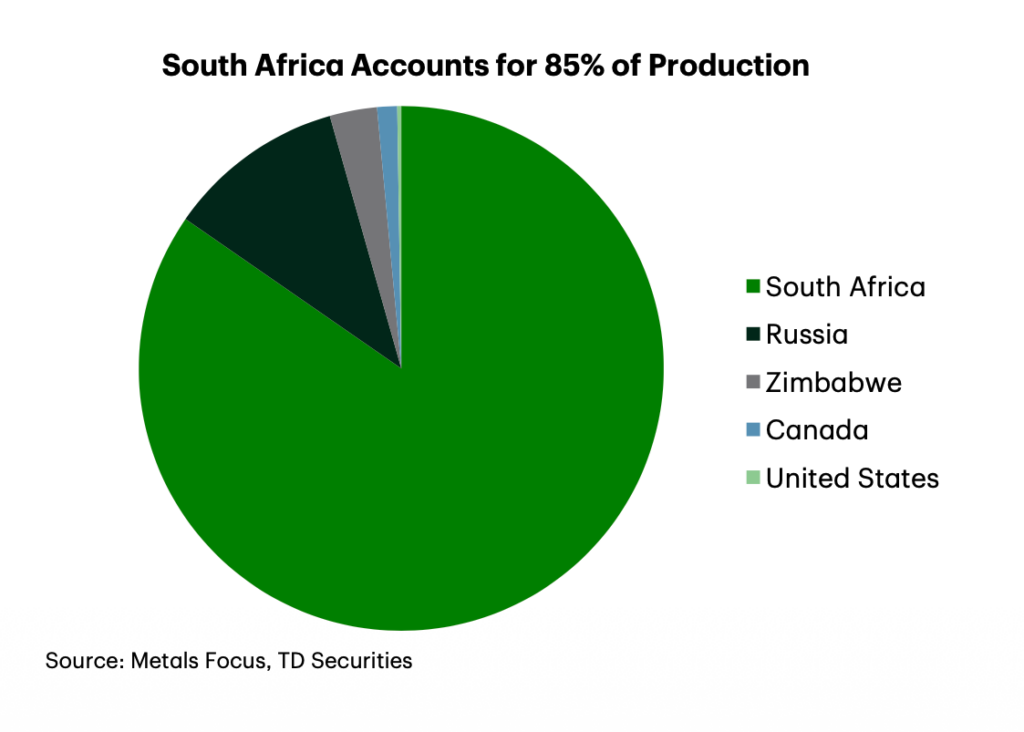
The vulnerability is heightened by extreme geographic concentration. South Africa supplies about 85% of the world’s primary rhodium, while only five of the country’s PGM mines account for roughly half of global output. Smaller South African operations, along with mines in Russia and Zimbabwe, produce most of the remainder.
Rhodium supply also responds poorly to its own price because the metal is largely produced as a by-product of platinum and palladium mining. Rhodium represents only about a quarter of mined PGM revenue, leaving development and production decisions primarily dependent on the economics of the broader PGM basket.
That structure creates an unusual market dynamic: falling rhodium demand may produce a surplus without necessarily encouraging miners to rapidly cut output, while supply disruptions can still have an outsized effect because inventories offer such a small buffer.
Auto slowdown
Demand presents the more persistent challenge. Autocatalysts account for most rhodium consumption, tying the metal closely to internal combustion engine vehicle production.
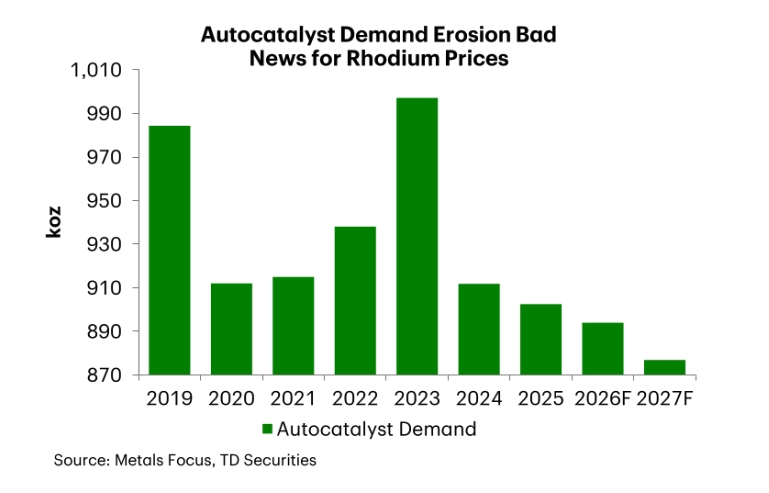
After years of expansion, autocatalyst demand has flattened as electric vehicles take a larger share of the automotive market. TD expects declining ICE vehicle sales to weigh further on rhodium consumption over the coming years.
Slower-than-anticipated EV adoption should temper that decline in the near term and reduce the likelihood of a prolonged price collapse. Longer vehicle lifespans also delay the return of rhodium contained in older catalytic converters to the recycling market.
Secondary supply should nevertheless increase steadily as older vehicles carrying heavier rhodium loadings reach the end of their lives. High metal prices have also encouraged greater recovery from scrap, although recycling remains constrained by imperfect recovery rates and limited processing equipment in some vehicle-retirement markets.
Substitution offers another potential pressure valve, but replacing rhodium is neither quick nor straightforward. Palladium is the usual alternative, yet TD estimates implementation can take 18 to 24 months and require five to eight times as much palladium as the rhodium being replaced.
Investors, meanwhile, have begun returning to the market. Rhodium exchange-traded funds have recorded positive inflows for the first time in more than a decade as retail and institutional investors seek physical precious-metals exposure.
Holdings remain well below levels reached in the early 2010s, leaving the market caught between weakening structural demand and a supply chain with little margin for error. The result could be lower prices over the next several years punctuated by abrupt rallies whenever production falters.
Source: https://www.mining.com/td-sees-rhodium-surplus-ending-four-year-squeeze/