

A prolonged disruption around the Bab el-Mandeb Strait, a chokepoint for Red Sea maritime traffic, could squeeze mining supply chains well beyond oil and gas, raising costs and delaying critical inputs ranging from sulfuric acid and explosives feedstock to battery materials, according to GEM Mining Consulting.
The Chile-based consultancy estimates that a 90-day disruption could affect 38.9 million to 77.8 million tonnes of modelled commodity and input flows, with a central scenario of 61.1 million tonnes. Mine production potentially exposed to input delays ranges from 0.8 million to 13.8 million tonnes, while delayed demand ranges from 12.6 million to 33.7 million tonnes.
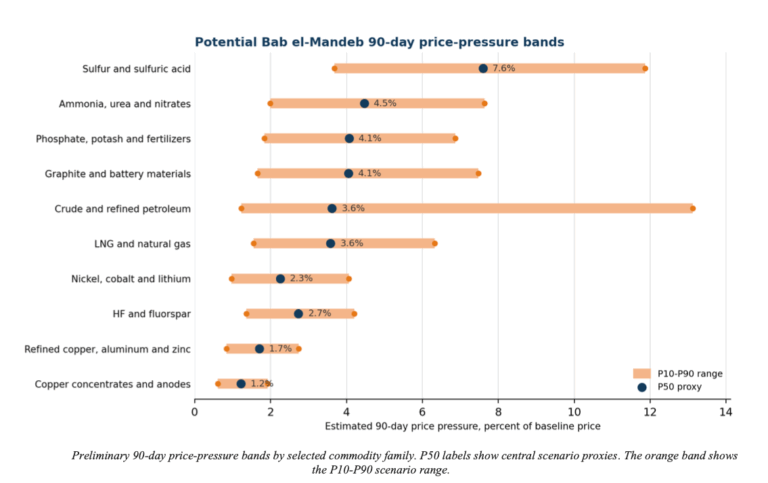
The modelling puts the value-weighted price-pressure range at 1.2% to 10.5%, with a central scenario of 3.4%. Associated cost premiums range from $480 million to $2.48 billion, with the central case at $1.37 billion.
The assessment comes as Yemen’s Iran-backed Houthi militants expand their control around Bab al-Mandeb, one of the world’s most important maritime chokepoints, adding urgency to questions over how prolonged shipping disruptions could spread from energy into mining and other industrial supply chains.
Red Sea chokepoint
Yemen Houthi militants have seized the Greater and Lesser Hanish islands in the Red Sea, strengthening their position around the shipping corridor after earlier taking the port of Mokha and strategic Perim Island in and around the Bab al-Mandeb Strait. The advances have heightened concerns over the group’s ability to disrupt maritime traffic through the region.
Bab al-Mandeb is a narrow passage separating the Arabian Peninsula from Africa and forming the southern gateway to the Red Sea. From the Gulf of Aden and Indian Ocean, ships passing through the strait can travel north through the Red Sea and Suez Canal to reach the Mediterranean, making the passage a critical link between Asian, Middle Eastern and European markets.
Roughly 10% of global maritime trade passes through Bab al-Mandeb, underscoring the potential consequences of a prolonged closure or disruption. The route has become even more important for energy markets during the current Middle East conflict as Saudi Arabia has redirected crude through the Red Sea amid disruption at the Strait of Hormuz.
The Houthi advances have already contributed to concerns over an oil supply crunch. But GEM’s analysis suggests the consequences for the resources sector could extend further, as disruption works its way through freight rates, insurance, inventories and the chemicals and materials needed to keep mines and processing plants running.
GEM’s preliminary assessment covers 15 commodity and input families and suggests the main threat to miners would come from higher delivered costs, longer transit times, insurance premiums and working-capital requirements rather than a broad global shortage of minerals.
Ships can divert around southern Africa when the passage becomes unreliable, but doing so extends voyages and vessel cycles while affecting insurance costs, inventories and the availability of containers and specialized vessels.
Critical inputs
GEM identifies sulfur and sulfuric acid, ammonia and nitrates, phosphate and potash fertilizers, graphite and battery-material intermediates, petroleum products and LNG among the more exposed markets. Their vulnerability reflects a combination of route dependence, limited short-term substitution and their importance to industrial processes.
The effect would not be uniform across commodities. An input representing a relatively small share of global trade could still disrupt an operation if it is continuously consumed, difficult to replace or held in limited inventories.
Sulfuric acid, for example, is an essential processing input at some mining operations, while ammonia and nitrates feed into explosives supply chains. Specialty reagents and some battery-chain materials can also depend on concentrated suppliers and specialized logistics.
GEM’s exposure heat map assesses commodity families across six factors: route share, difficulty switching suppliers, inventory risk, market balance, freight risk and links to industrial processes. Scores range from one for lower exposure to five for higher exposure.
Petroleum products, LNG, sulfuric acid, ammonia, reagents, graphite, battery intermediates, rare earths and equipment spares rank among the more vulnerable categories because shipping disruptions can combine with limited inventories, concentrated supply or direct operating requirements.
Large bulk markets including iron ore, metallurgical coal, bauxite and alumina appear less exposed in GEM’s initial screening. Alternative routes, inventories and deeper markets could absorb more of the disruption, although freight costs could still rise.
The estimates are scenario bands rather than forecasts. GEM describes its P10, P50 and P90 figures as communication proxies that should not be interpreted as statistical quantiles until route shares, delays, inventory coverage, elasticities and cost pass-through assumptions are calibrated with distributional data.
Building resilience
The analysis suggests mining companies may need to treat maritime chokepoints as an operating risk rather than simply a geopolitical or energy-market issue.
Companies could map shipping routes for critical supplies, stress-test inventory coverage and determine which mines or processing facilities would encounter constraints first under disruptions lasting 30, 90 or 180 days. Backup suppliers and logistics options could become particularly important for inputs with few substitutes.
Governments could similarly incorporate strategic maritime routes into mineral-security planning through improved trade-flow transparency, customs and vessel-tracking data, inventories of critical inputs, port contingency planning and international maritime-security coordination.
Source: https://www.mining.com/red-sea-disruption-puts-global-mining-supplies-at-risk/